A quarter-point increase rooted in an oil shock
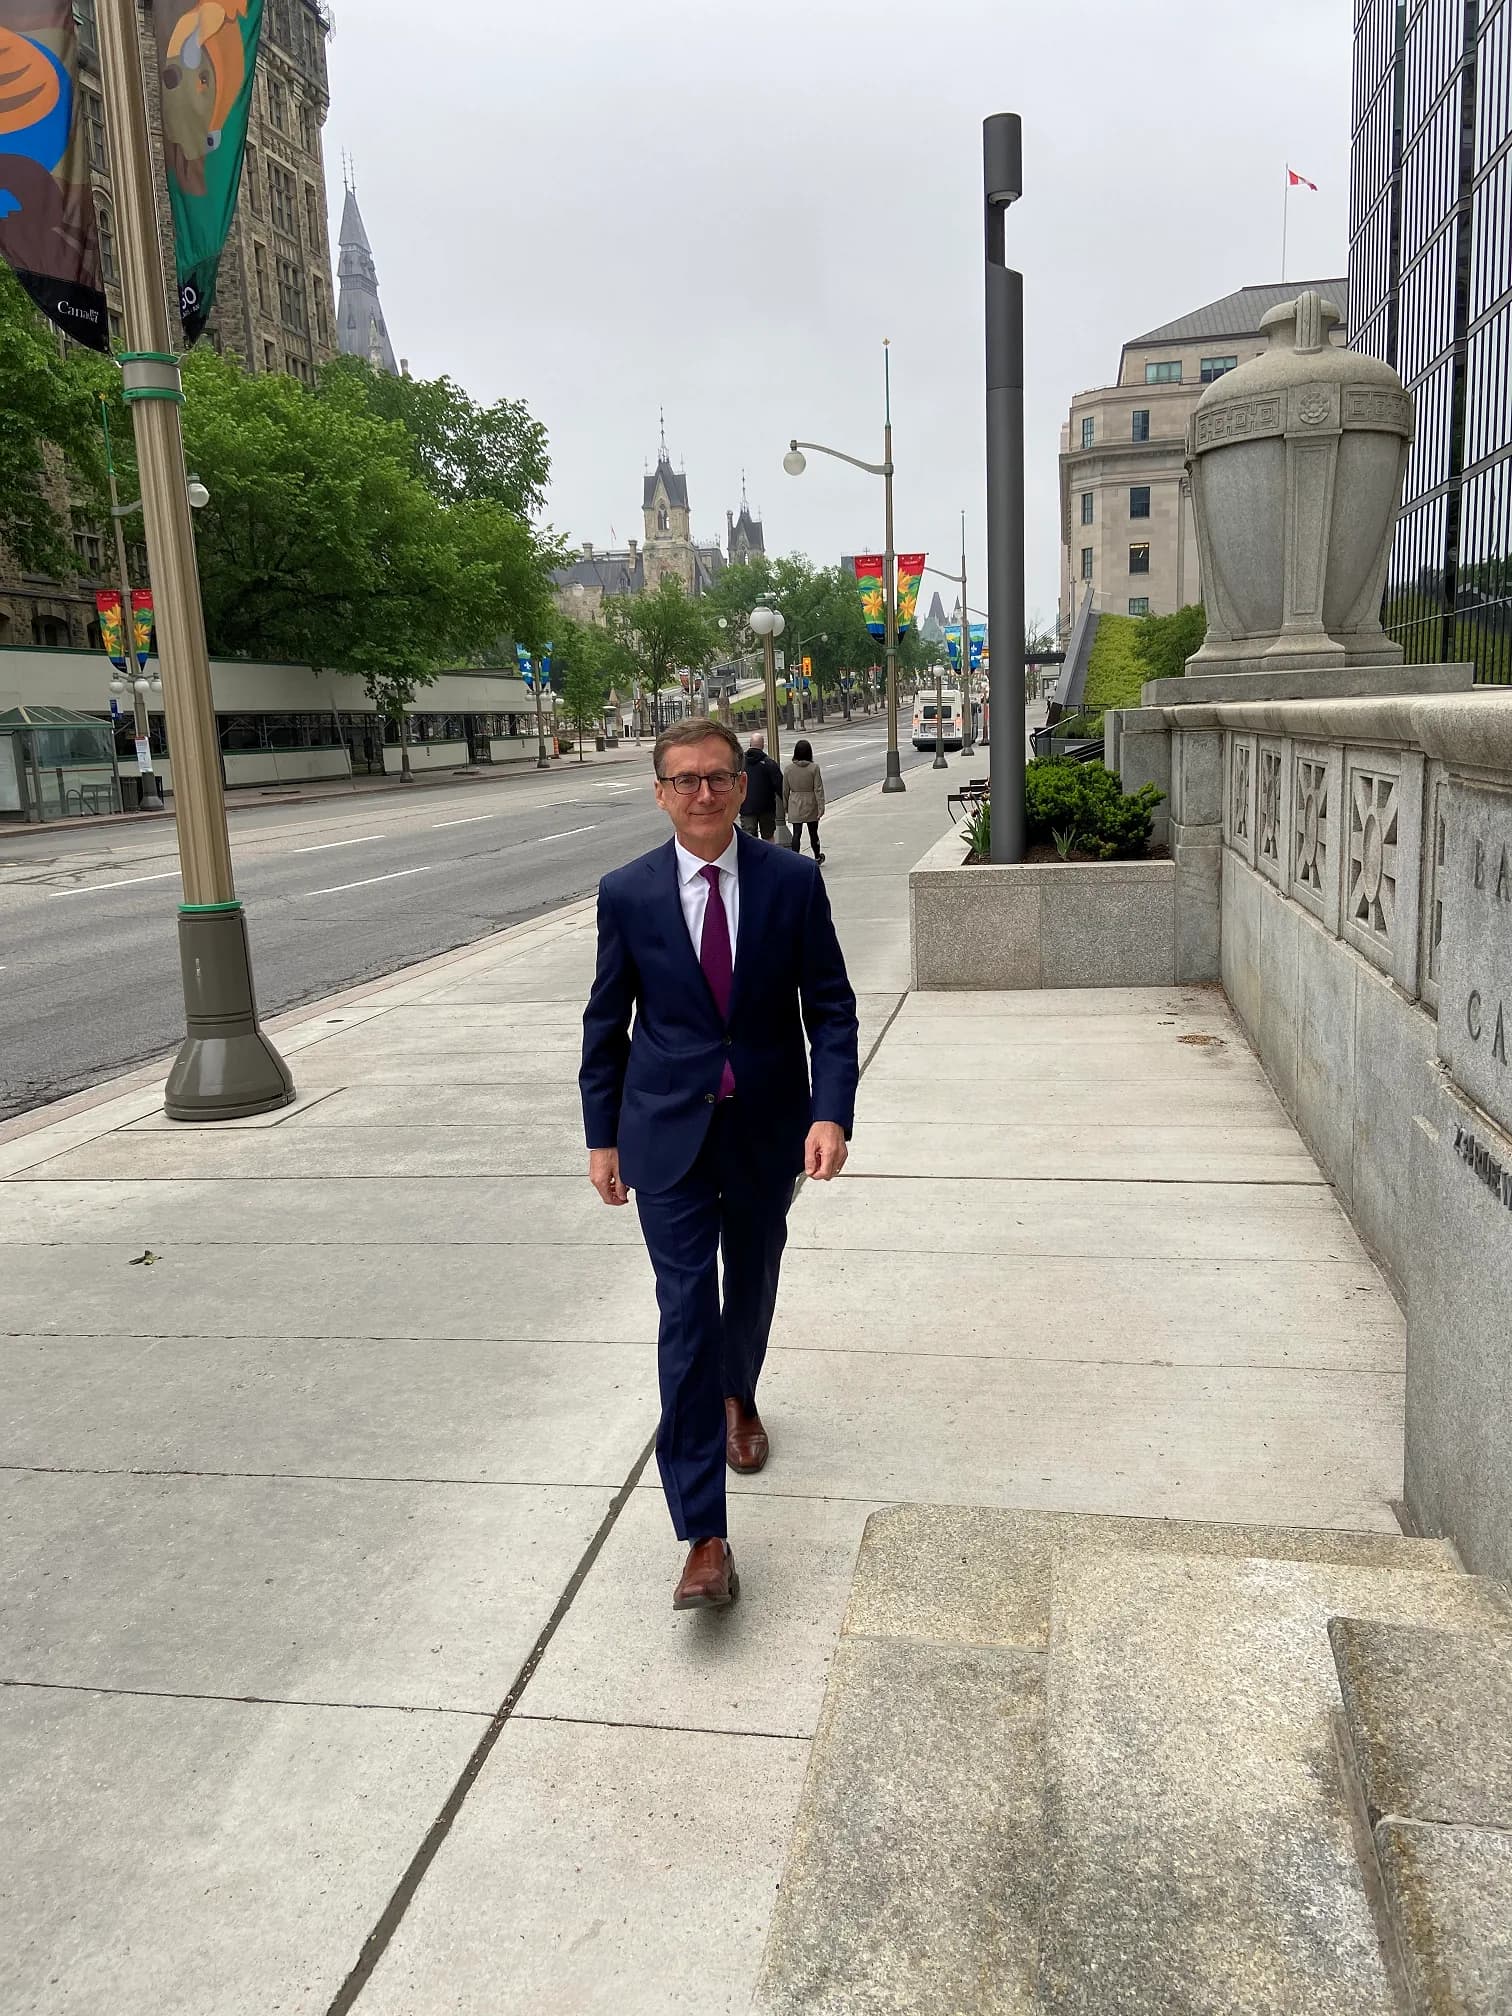
On October 28 the Bank of Canada lifted its policy rate by a quarter point to 2.5%, the first tightening move since July 2023. Governor Tiff Macklem, joined in Ottawa by Senior Deputy Governor Carolyn Rogers, cast the step as a reaffirmation of the central bank's dedication to price stability amid what he called a period of global upheaval, citing an oil shock rooted in the Middle East and fluid trade ties between Canada and the US.[S1][S4][S6]
Two shifts since July 2026 drove the Governing Council's thinking, according to Macklem: a weaker inflation outlook, with oil prices expected to stay elevated for an extended period while the Middle East conflict continues, and a domestic recovery that has proven sturdier than expected despite US tariff pressure. He acknowledged that uncertainty remains high and that both the Middle East situation and Canada-US trade relations are still in flux.[S1]
Inflation near 3% with a long road to target
Since April, CPI inflation has remained close to 3%, and the Bank expects it to climb to about 3.5% by the close of the year; returning to the 2% goal is not anticipated before mid-2028. Stripping out gasoline, CPI is at 2.2%, and core inflation is running near 2%. Macklem warned that the longer energy costs stay elevated, the more likely they are to feed through into a wider range of consumer prices.[S1]
Balancing that danger, the Council pointed to healthy economic data. GDP grew 3.3% in the second quarter, and early signals suggest roughly 2% growth in the third, per the Bank of Canada's October 2026 Monetary Policy Report. The jobless rate has held around 6.5%, while growth for all of 2026 is projected at only 1%, held back by US tariffs.[S1]
An economist argues for patience
Not every forecaster backed the timing. Stéfane Marion, chief economist at National Bank of Canada in Montréal, told the Mortgage Professionals Canada conference in Calgary the previous week that the underlying data favored waiting. He noted that core inflation remains at 2% and argued the central bank should not tighten on October 28, adding that any increase ought to be modest.[S1]
What it means for mortgage borrowers
For Canadian mortgage brokers, the decision changes client conversations at once. Holders of variable-rate mortgages will pay more as lenders' prime rates shift from 4.45% to 4.70%, a move that renewal talks and rate-path planning had been anticipating all year and that the announcement now accelerates. Leah Zlatkin, a Toronto licensed mortgage broker and commentator with LowestRates.ca, said a single increase is unlikely to stand alone and that she expects a cycle if a hike occurs.[S1]
Marc Ercolao, an economist at TD Bank in Toronto, noted that Macklem had effectively previewed the outcome weeks earlier, saying the Governor's prior comments likely tilted the decision toward tightening. Ercolao added that the Bank sees no obvious end to the Middle East conflict and is growing more worried about inflation risks. The Council made no pledge on future steps; Macklem said each meeting would be judged on its own, that further increases are possible, and that the Bank would proceed cautiously amid uncertainty. The next announcement is set for December 9.[S1][S2][S3][S7]